
Faster than a bank. Easier than a bank.
The Lendmax Flexline is a home equity line of credit against the value of your home. Draw what you need, when you need it, and pay interest only on what you take.
No cost to find out · No income documents · Soft credit check first
Your equity, without moving your mortgage.
Four things make it different from a line of credit at a bank.
Your mortgage stays put
The Flexline can sit behind the mortgage you already have, or take first position if your home is paid off. Either way you keep the lender you have.
You pay for what you use
Draw $20,000 from a $200,000 line and you are charged interest on $20,000. The rest waits there and costs you nothing.
No income documents
No pay stubs, no notices of assessment, no T4s. Your home and the equity in it are what the decision rests on.
No penalties, ever
Pay it down, pay it off, draw it again. Nothing is charged for repaying early. Choose a one, three or five year term to suit your plans.
Everything costs more. Your equity hasn't moved.
If you have owned your home a while, the value sitting in it has gone one way while the cost of everything else has gone the other. A Flexline is one way to reach it without selling or refinancing.
- Consolidating higher-rate debt into one monthly cost
- A renovation, a repair, or a bill that will not wait
- A standby line you open now and only draw on if you need it
A Flexline is secured against your home. It suits a planned need or a buffer, not day-to-day spending — and if you cannot repay it, your property is at risk.
One line of credit, a lot of reasons.
You do not have to say what it is for to be approved, and you do not have to use it all at once. These are the reasons homeowners open one.
Debt consolidation
Roll several higher-rate balances into one monthly cost.
Credit card payoff
Clear revolving balances charging you 20% or more.
Personal loan payoff
Retire a term loan early without a prepayment charge.
CRA arrears
Settle a tax balance before interest and collection build.
Renovation or repair
A kitchen, a roof, a basement, or the thing that cannot wait.
Medical and dental
Treatment, surgery or care that is not covered.
Education
Tuition, a program, or a year abroad for your kids.
A wedding
Pay for it over time instead of draining savings.
Travel
A trip you plan for, drawn and repaid deliberately.
Down payment
Equity for a second property, a cottage, or a rental.
Business working capital
Bridge a slow quarter or fund stock, tools or payroll.
An investment opportunity
Capital in hand when something will not wait for a bank.
Whatever you use it for, a Flexline is secured by a charge on your home. Draw it for something you have a plan to repay — if you do not keep up the payments, your property may be at risk.
How much could you open up?
Move the two sliders. Everything else works itself out.
Slide all the way to $0 if your home is paid off. The Flexline works either way.
You never have to take the whole line.
With a mortgage still owing, the Flexline takes second position. That rate is set after we review the file, so it is not published — submit an inquiry and it comes back with your offer.
Based on borrowing up to 75% of your home's value, interest only on what you use. A payment figure is shown only where the Flexline would take first position, at 6.49%; second-position pricing is set after review and is not published. The $2,499 setup fee and legal fees are extra, so your total cost of borrowing is higher than the interest rate. This is an estimate to help you think, not an offer of credit.
Flexline at a glance.
The whole product on one page, so there is nothing to find out later.
| Credit limit | Up to $1,500,000 |
|---|---|
| Position | First or secondBehind your existing mortgage, or on its own if the home is paid off |
| Maximum loan-to-value | Up to 75%Of the appraised value, including anything already registered |
| Terms available | 1, 3 or 5 years |
| Interest rate | First position from 6.49%Second position is priced after review and is not published — submit an inquiry for your rate |
| Interest charged on | The drawn balance onlyMonthly. Undrawn room costs nothing |
| Setup fee | $2,499 |
| Prepayment penalty | None |
| Income documents | Not required |
| Where we lend | Ontario, British Columbia, Alberta* |
*Product may vary due to provincial regulatory requirements. The equity line may not be available for all property types or in all cities. Other fees may apply.
Second-position pricing is set after review of the file, so it is not published. Submit an inquiry and your rate comes back with your offer.
Four steps, and most of a week.
A home equity line at a bank often takes six to eight weeks. The slow parts here have been replaced, not rushed.
Tell us about your home
Your name, your address, and roughly what you think it is worth. Takes about two minutes.
We check the value
Based on your location in Ontario, British Columbia or Alberta, we use desktop and full appraisals to price your offer and your loan-to-value. Most are processed the same day or within two business days.
Your offer comes back
Your limit, your rate, your term. Adjust it and see the numbers move before you commit to anything.
Sign and get funded
You sign with your own lawyer, the line opens, and the money lands. As few as five days from start to finish.
Transfer, track or pay from anywhere, anytime.
Once the line is open, everything happens in your account. No branch, no phone queue.
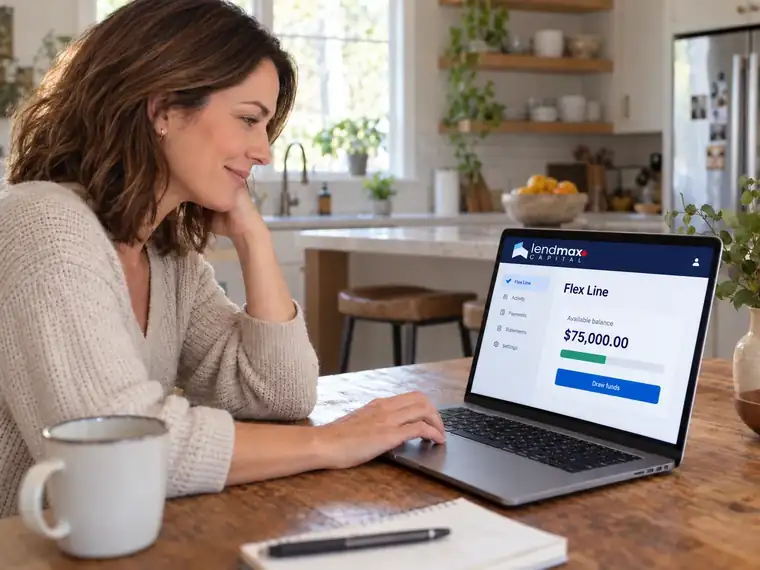
Online access
Sign in from a phone, tablet or computer and see your balance, the room you have left, and every draw and repayment since the line opened.
Convenience
Move a draw to your bank account, or make a payment, whenever it suits you. Nothing needs a call, an appointment or a signature.
Monthly statement
A statement every month setting out the interest charged, the payments received and your closing balance, so the cost is never a surprise.
Same security. A very different process.
A bank line is a fine product if you fit the box and can wait.
| Your bank | Lendmax Flexline | |
|---|---|---|
| Time to funding | Six to eight weeks is common | As few as 5 days |
| Income documents | Pay stubs, T4s, notices of assessment, bank statements | None required |
| Stress test | Applies, and can reduce or refuse the line | Not applied |
| Your existing mortgage | Usually has to move to the same lender, which can mean breaking it | Stays exactly where it is |
| If you are self-employed | Often the hardest file in the branch | Treated like any other file |
| Appraisal | Full appraisal, booked and paid before you get an answer | Desktop and full appraisal, usually same day |
| Cost to get an answer | Appraisal fee often payable upfront | Nothing |
| Position available | First position only, in most cases | First or second |
| Prepayment penalty | Varies by product | None |
| Interest charged on | The drawn balance | The drawn balance — the same |
| Interest rate | Starts around 5.2% if you qualify and can wait | First position from 6.49%. Second position priced on review, and shown before you spend anything |
Bank timelines, requirements and pricing describe common practice across Canadian institutional lenders and vary by lender, product and applicant. A bank line of credit is usually the cheaper option if you meet its criteria and can wait for it. Compare the offer actually in front of you.
What clients say.
Left empty on purpose.
Writing testimonials would mean inventing customers, and a review nobody wrote has no place on a page about borrowing against a home. The space is built and ready. Two ways to fill it:
- Pull them in live from the Lendmax Google Business Profile, so the rating and the words are always the real ones.
- Send me real ones you already have, with the first name and date as written.
Request a callback.
Tell us when suits you and someone from the desk calls. No documents, no credit pull to have the conversation.
Home equity lines of credit, explained.
What a HELOC is, how much of your home equity you can borrow in Canada, what it costs, and where the Lendmax Flexline differs.
What a home equity line of credit is
What is a home equity line of credit (HELOC)?
A home equity line of credit is revolving credit secured against your home. Instead of receiving one lump sum, you are approved for a limit and draw from it whenever you want. You pay interest only on the amount you have actually taken out, from the day you take it out, not on the whole limit.
Pay some of it back and that room becomes available again, the way a credit card works, except the interest rate is far lower because your home is the security.
What is the Lendmax Flexline?
The Lendmax Flexline is our home equity line of credit for Canadian homeowners. It is designed for people who have equity in their home but do not fit the bank's paperwork: self-employed income, commission income, a credit file that has had a rough year, or simply no time to wait six weeks for an answer.
The Flexline goes to 75% of your home's value, needs no income documents, and does not apply the mortgage stress test. It can sit in first position, or in second position behind a mortgage you want to keep exactly where it is.
How is a HELOC different from a home equity loan or a second mortgage?
A home equity loan, often registered as a second mortgage, is a fixed amount advanced once. You start paying interest on all of it immediately, and once you pay it down you cannot take it back out without a new application.
A HELOC is a limit you can draw against, repay and draw again. If you need $60,000 now and might need another $100,000 in eight months, a line costs you nothing on the unused portion in the meantime.
How does a HELOC work month to month?
You draw what you need, and interest is charged only on the balance you are carrying. Your monthly obligation is the interest on that balance. There is no fixed amortised payment forcing principal down, so a month where you draw nothing is a month with nothing to pay.
You get online access to transfer, track and pay from anywhere, and a monthly statement showing exactly what was drawn, what was repaid and what interest was charged.
How much home equity you can borrow
How much can I borrow against my home equity in Canada?
At a federally regulated bank, a revolving home equity line of credit is capped at 65% of your home's value. A HELOC combined with a mortgage at the same institution can reach 80% of the value in total, but the revolving portion still cannot exceed 65%, and the stress test applies to the whole thing.
A Lendmax Flexline goes to 75% of your home's appraised value, counting every charge already registered against the property, to a maximum limit of $1,500,000. Your actual limit comes from the valuation, your credit and where the property is.
How do I calculate my home equity?
Take what your home would sell for today and subtract everything owing against it, including your mortgage and any secured line already registered. What is left is your equity.
To estimate a Flexline limit, multiply the value by 0.75 and subtract the balances still owing. The sliders above do that arithmetic for you.
Can I get a HELOC if I still have a mortgage?
Yes. The Lendmax Flexline is registered separately and sits in second position behind your existing first mortgage. You do not move it, break it, or pay a penalty on it — which is the usual catch when a bank offers you a line of credit.
If your home is paid off, the Flexline takes first position and stands on its own.
Can I get a home equity line of credit with bad credit or without income documents?
The Flexline is underwritten primarily on the property and the equity in it, so there are no income documents to upload and the mortgage stress test is not applied. Credit is still reviewed, and it affects your rate and your limit, but a bruised file is not automatically a decline the way it often is at a branch.
The honest limit: there has to be real equity. If there is not enough room between your home's value and what is already owing, no structure fixes that.
What it costs
What interest rate does a HELOC charge?
Most bank HELOCs carry a variable rate tied to that lender's prime rate — prime plus a set amount — so the rate moves whenever prime moves. Federally regulated institutions have to notify you in writing within 30 days of a rate change.
Lendmax Flexline rates start at 6.49% in first position. Second-position pricing is set after a review of the file and is not published, for the reason in the next answer.
Why can't I see a rate for a second position?
Because it genuinely depends on the file. A second position sits behind an existing mortgage, so the rate turns on how much is ahead of it, the combined loan-to-value, the property type and your credit. Publishing one number would be a guess, and you would be the one it was wrong for.
Submit an inquiry and your rate comes back with your offer, itemised alongside every fee, before you commit to anything and before you spend a dollar.
What will a Lendmax Flexline cost me in total?
Interest on what you actually draw, a $2,499 setup fee, and legal fees payable to your own lawyer. Other fees may apply depending on the file.
Those fees are why your total cost of borrowing is higher than the interest rate alone. Five worked APR examples show exactly how that arithmetic lands at different amounts. Your own annual percentage rate and every fee are stated in your offer before you sign.
Is HELOC interest tax deductible in Canada?
Generally only when the borrowed money is used to earn income from a business or from property — not when it is used for personal purposes such as renovations, a vehicle or consolidating consumer debt. The use of the funds decides it, not the fact that the loan is secured by your home.
Whether your situation qualifies, and what records the Canada Revenue Agency expects you to keep, is a question for your accountant or tax adviser. We are not tax advisers and nothing here is tax advice.
Applying
Will applying hurt my credit score?
No. The first step is a soft credit check, which does not affect your score. A full check only happens later, after you have seen your offer and decided to go ahead.
How fast can I get a home equity line of credit?
At a bank, six to eight weeks is common once the appraisal, the income review and the stress test are done. A Lendmax Flexline is approved on a soft credit check and a desktop appraisal, usually the same day or within two business days, and the fastest files fund in as few as five days.
Five days is the fastest case, not a promise. Every file is subject to underwriting, valuation, title review and approval, and no credit is approved until a written commitment is issued.
Do I need an appraisal?
Yes. We use a desktop appraisal on most files and a full appraisal where the property, the location or the amount calls for one. Either way we order it, and most come back the same day or within two business days.
The appraisal is what sets your loan-to-value, so it decides both your limit and your rate. You are told which one your file needs before anything is booked.
How long is the term, and what happens at the end of it?
One, three or five years, whichever suits your plans. There is no prepayment penalty on any of them, so you can pay the balance to zero and draw it again inside your term.
At the end of the term the balance is due, and the usual paths are to renew, to pay it out with longer-term financing, or to pay it off from the proceeds of a sale. We talk about which one you are aiming at before you start, not at the end.
What can I use a home equity line of credit for?
Whatever you need it for: catching up on bills, consolidating higher-rate consumer debt, renovations, tuition, a tax balance, bridging a gap in self-employed income, or keeping a business steady through a slow quarter. You draw what you need and leave the rest alone.
What it is not good for is treating equity as income. Your home is the security, so if you cannot keep up the payments your property may be at risk — which is why we would rather talk through the plan for paying it back before you draw.
Where does Lendmax lend?
Ontario, British Columbia and Alberta. The product may vary by province due to regulatory requirements, and the Flexline may not be available on all property types or in all cities.
Where your home is affects both your limit and your rate, because how readily a property would sell is part of how it is priced.
Find out what your home can do.
No documents to dig up. No cost to get your number.